
Commercial Loan Rates Multifamily – Complete USA Guide for Apartment Financing
Multifamily real estate stayed attractive even when other property sectors struggled.
People always need places to live.
Office buildings took hits after remote work exploded. Retire properties fought ecommerce pressure. But apartment demand kept moving because housing shortages across the United States never fully cooled down.
That’s why investors keep searching for one thing constantly:
Commercial Loan Rates Multifamily
Because financing decides whether a deal works or quietly turns into a financial migraine wrapped in paper work.
And honestly, multifamily financing got more complicated over the last few years.
Interest rates shifted.
Insurance cost claimed
Banks Tightened Lending
Property Prices stayed high in Many Cities.
So, investors now pay much closer attention to financing details than they did during the easy money years.
Makes sense.
One bad loan structure can crush cash flow for a property that looked profitable on paper.
What Multifamily Commercial Loans Actually are
A multifamily commercial loan finances residential properties with multiple housing units.
Usually five units or more
That includes:
- Apartment Complexes
- Mixed use Buildings
- Student Housing
- Large Residential Rental Properties
Properties with 1-4 units often fall under residential mortgage rules instead of commercial lending.
Once buildings cross into 5+ units lenders usually treat them as commercial real estate.
And commercial lending works differently.
A lot differently.
Buy Multifamily Properties Attract Investors
Rental income creates recurring cash flow
That’s the main attraction
People also like multifamily properties because risk spreads across tenants. If one renter leaves a 20 unit building, the property still generates income from the remaining units.
Compare that with a single family rental
One vacancy means 100% income loss temporarily.
Big difference
Multifamily Properties also gained popularity because housing demand stayed strong across major US cities. Especially in places with population growth like Texas, Florida, Arizona, North Carolina.
Current Commercial Loan Rates Multifamily in 2026
Rates change constantly
That frustrates investors because timing matters heavily in commercial real estate.
As of 2026, many multifamily commercial loan rates in the USA generally range between:
| Loan Type | Estimated Rate Range |
| Bank Multifamily Loans | 5.8% to 8.5% |
| Agency Loans (Fannie Mae / Fraddie Mae) | 5.2% to 7.2% |
| Bridge Loans | 8% to 12% |
| Hud Multifamily Loans | 4.9% to 6.8% |
| CMBS Loans | 6% to 8.7% |
Rates depend on several factors:
- Credit Score
- Property Location
- Occupancy Rate
- Loan Amount
- Debt Coverage Ratio
- Market Conditions
And yes, lenders absolutely judge properties harder now then they did during low rate years.
Why Multifamily Loan Rates Increased
The Federal Reserve affected borrowing costs heavily after inflation surged earlier in the decade.
Cheap debt disappeared.
That changed investor behaviour immediately.
Properties that looked profitable at 3% interest suddenly looked for less attractive at 7% or 8%.
Some investors stopped buying entirely. Others shifted towards smaller deals, some sellers refused to lower prices and just waited.
The market got awkward for a while.
Still kinda is in certain cities.
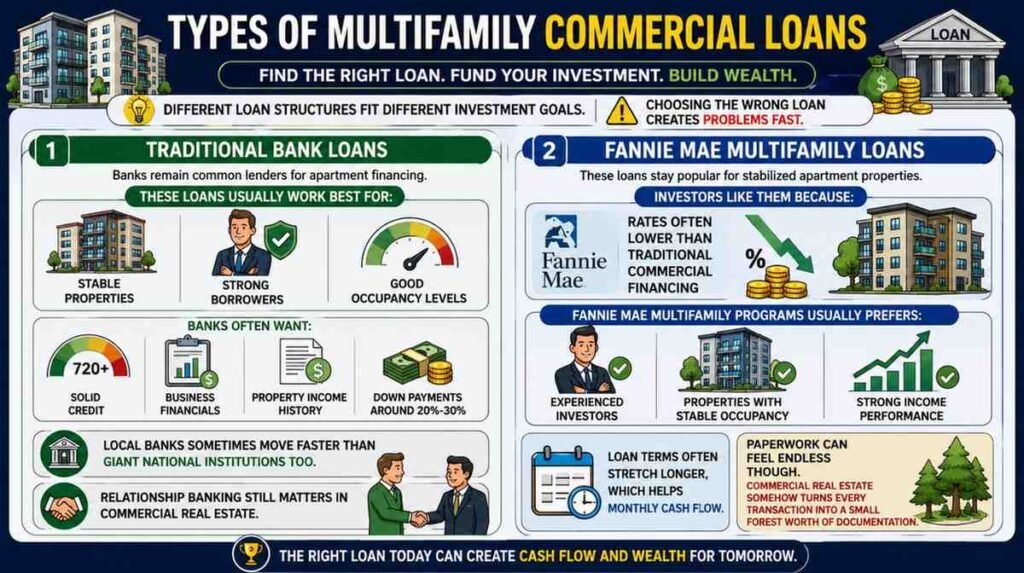
Types of Multifamily Commercial Loans
Different loans structures fit different investment goals.
Choosing the wrong loan creates problems fast
Traditional Bank Loans
Banks remain common lenders for apartment financing.
Those loans usually work best for:
- Stable Properties
- Strong Borrowers
- Good Occupancy Levels
Banks often want:
- Solid Credit
- Business Financials
- Property Income History
- Down payments Around 20%-30%
Local banks sometimes move faster than giant national institutions too.
Relationship banking still matters in commercial real estate.
A lender who knows your track record may approve deals more comfortably.
Fanny Mae Multifamily Loans
These loans stay popular for stabilized apartment properties.
Investors like them because rates often land lower than traditional commercial financing.
Fanny Mae Multifamily programmes usually prefers:
- Experienced Investors
- Properties with Stable Occupancy
- Strong Income Performance
Loan terms often stretch longer to which helps monthly cash flow.
Paper work can feel endless through.
Commercial real estate somehow turns every transaction into a small forests worth of documentation.
Freddie Mac Multifamily Loans
Freddie Mac works similarly to Fannie Mae.
Both support multifamily housing markets heavily in the USA
Freddie Mac loans often attract borrowers seeking:
- Long-term financing
- Predictable rates
- Apartment refinancing
These programs remain major players in multifamily lending because they support liquidity in housing markets nationwide.
HUD Multifamily Loans
HUD financing usually attracts long-term apartment investors
Especially those holding properties for many years
Benefits may include:
- Lower rates
- Long amortization periods
- Non-recourse structures in some cases
But approvals take time.
A lot of time.
HUD paper work can test human patience in ways previously thought impossible.
Still, experienced investors tolerate the process because the financing terms sometimes become extremely attractive.
Bridge Loans for Multifamily Properties
Bridge loans work differently.
These short-term loans help investors buy or renovate properties quickly before refinancing later.
Common situations include:
- Value-add apartment deals
- Properties with vacancies
- Buildings needing repairs
Bride loans move faster but rates run higher
Lenders charge more because risk increases
Some investors use bridge loans aggressively during renovation projects, then refinance into long-term debt after improving occupancy and rental income.
What Lenders Check Before Approving Loans
Commercial lenders care about the property itself more than residential mortgage lenders usually do
The building needs to make financial sense.
Debt Service Coverage Ratio (DSCR)
This matters massively
Lenders calculate whether property income comfortably covers loan payments
Many banks want DSCR around 1.20 to 1.30 minimum
That means the property generates 20% to 30% more income than required debt payments.
Low DSCR numbers make lenders nervous quickly
Occupancy Rate
Empty apartments scare lenders
Stable occupancy helps financing approval because income appears more predictable
A building sitting half vacant creates major risk concerns
Especially in weaker rental markets
Borrower Experience
First-time investors face tougher scrutiny
Experienced apartment owners usually access better financing terms because lenders trust their operational ability more.
Managing multifamily properties takes real skill
Tenant problems, maintenance, leasing, insurance, claims, repairs, late payments. Things get messy fast.
Credit Score
Commercial lenders still care about personal credit heavily
Strong scores improve approval odds and interest rates.
Lower scores increase costs because lenders price loans based on perceived risk.
Pretty standard finance logic
Multifamily Loan Down Payments
Commercial multifamily loans usually require bigger down payments than residential homes.
Common ranges include:
| Property Type | Typical Down Payment |
| Stabilized apartments | 20% to 25% |
| Riskier properties | 25% to 35% |
| Bridge financing deals | 30%+ sometimes |
Lenders want borrowers financially invested in deals
Large down payments reduce lender exposure if project fail.
Fixed vs Variable Interest Rates
This decision matters more than beginners realize
Fixed Rates
Monthly payments stay predictable
Investors like stability, especially during uncertain rate environments
Long-term apartment owners often prefer fixed structures because budgeting becomes easier
Variable Rates
Rates fluctuate based on market indexes
These loans sometimes start cheaper initially
Then conditions change and payments climb
Aggressive investors occasionally prefer variable rates for short-term strategies, especially if they plan to refinance or sell quickly
Still risky.
Interest rate swings can destroy projected profits surprisingly fast.
Refinancing Multifamily Properties
A lot of apartment investors refinance eventually
Reasons include:
- Lower rates
- Pulling our equity
- Extending loan terms
- Funding renovations
Refinancing became harder after rates climbed because many owners previously locked extremely cheap debt years ago.
Replacing a 3.4% loan with a 7% loan feels financially painful
Some investors simply delayed refinancing altogether hoping rates ease later.
Best US markets for Multifamily Investing
Certain regions continue attracting investors heavily
Texas
Dallas, Austin, Houston, and San Antonio stayed active because population growth remained strong.
Job growth supports apartment demand consistently
Florida
Florida keeps attracting retirees, remote workers, and businesses
Cities like Tampa, Orlando, and Miami continue seeing apartment development and investor interest
Insurance costs became a major issue there though
Very Major
North Carolina
Charlotte and Raleigh gained strong multifamily attention because of tech growth and corporate expansion
People relocating from higher-cost states helped rental demand too
Arizona
Pheonix remains a large apartment investment market due to population growth and housing demand
Heat levels there still feel like someone accidentally left Earth too close to the sun during summer months.
Still, people keep moving there.
What Lenders Look For
| Factor | What Lenders Consider |
| Credit Score | Borrower’s credit strength |
| DSCR | Whether property income covers debt payments |
| Occupancy | Stability of rental income |
| Property Income | Historical and current cash flow |
| Down Payment | Borrower’s financial contribution |
| Experience | Previous multifamily ownership/management |
| Financial Records | Organized and veifiable documentation |
| Property Management | Professional operational capability |
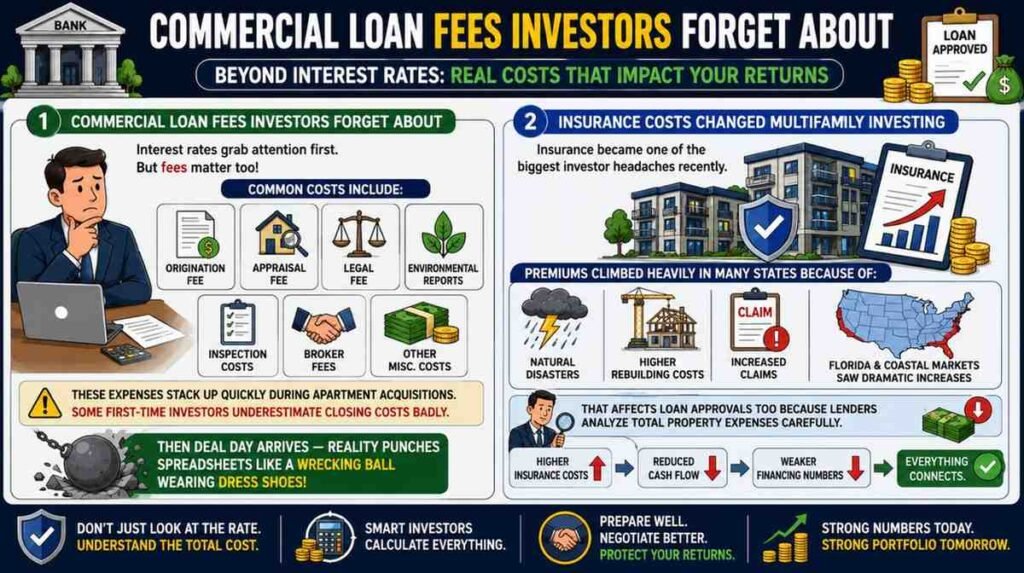
Commercial Loan Fees Investors Forget about
Interest rates grab attention first
But fees matter too
Common costs include:
- Origination fees
- Appraisal fees
- Legal fees
- Environmental reports
- Inspection costs
- Broker fees
These expenses stack up quickly during apartment acquisitions
Some first-time investors underestimate closing costs badly
Then deal day arrives reality punches spreadsheets like a wrecking ball wearing dress shoes
Insurance Costs changed Multifamily Investing
Insurance became one of the biggest investor headaches recently
Premiums climbed heavily in many states because of :
- Natural disasters
- Higher rebuilding costs
- Increased claims
Florida and coastal markets especially saw dramatic insurance increases
That affects loan approvals too because lenders analyze total property expenses carefully
Higher insurance costs reduce cash flow
Reduced cash flow weakens financing numbers
Everything connects.
Multifamily Investing Risks
Apartment investing can build wealth
Still comes with risk
Vacancy Risk
Economic downturns can reduce tenant demand
Large vacancy problems damage property income fast
Repair Costs
Roof replacements
Plumbing issues
HVAC systems
Parking lot repairs
Large apartment burn cash faster than beginners expect
Something always breaks eventually
Usually at the worst possible time too
Interest Rate Risk
Higher borrowing costs reduce profits
Some deals that looked amazing during low-rate periods stopped working completely after financing costs increased
Math changed, That Simple
How Investors Improve Multifamily Loan Approval Chances
A few things help substantially
Strong Financial Records
Lenders love organized documentation
Messy records slow approvals badly
Higher Down Payments
More borrower cash reduces lender risk
That often improves loan terms too
Stable Properties
Consistent occupancy and rental history strengthen applications significantly
Predictable income matters heavily in commercial lending
Professional Property Management
Lenders feel more comfortable when experienced management companies handle operations
Especially for larger apartment communities
Multifamily Real Estate Still Attracts Long-Term Investors
Even with higher rates, apartment investing remains active because housing demand continues across much of America
People need rentals
Population keeps growing in key states
Homeownership became harder for many households
That combination supports apartment demand
Commercial loan rates multifamily investors pay today definitely changed compared to earlier years. Deals require more careful analysis now. Investors can’t rely on ultra-cheap debt carrying weak properties anymore
Honestly, that probably cleaned up some reckless behavior from the market
The strongest multifamily investors today focus heavily on:
- Cash flow
- Occupancy
- Expense control
- Long-Term financing stability
Because apartment investing rewards discipline more than excitement.
And lenders know it.
Frequently Asked Questions
- What are commercial loan rates for multifamily properties in 2026?
The article gives an estimated 2026 range of 4.9% to 12%, depending on the loan type. HUD loans are listed at 4.9%-6.8%, while bridge loans are listed at 8%-12%. - What is multifamily commercial loan?
A multifamily commercial loan is financing for residential properties with multiple units, generally five or more units. Apartment complexes, student housing and large rental properties are common examples. - What factors affect multifamily commercial loan rates?
Rates can depend on the borrower’s credit, property location, occupancy rate, loan amount, DSCR and overall market conditions. - What down payment is required for a multifamily commercial loan?
The article lists typical down payments of 20%-25% for stabilized apartments, 25%-35% for riskier properties and sometimes 30% or more for bridge financing. - What is DSCR in multifamily commercial lending?
Debt Saving Coverage Ratio (DSCR) measures whether a property’s income is sufficient to cover its debt payments. The article says many lenders look for a DSCR around 1.20 to 1.30 higher. - What is the difference between bank, agency, HUD and bridge loans?
Traditional bank loans generally suit stable properties and strong borrowers. Fannie Mae and Freddie Mac programs are commonly used for stabilized apartments and longer term financing. HUD financing can suit long term apartment ownership, while bridge loans are typically used for acquisitions or renovations before refinancing. - Are fixed or variable rates better for multifamily properties?
Fixed rates provide more predictable monthly payments and can help with long term budgeting. Variable rates may initially be cheaper but can increase when market rates change, creating additional risk. - What costs should investors consider besides the interest rate?
Investors should also budget for origination, appraisal, legal, environmental report, inspection and broker fees. Insurance costs can also significantly affect a property’s cash flow and financing calculations. - How can I improve my chances of getting a multifamily commercial loan?
Strong financial records, a larger down payment, stable occupancy, consistent rental income and professional property management can strangthen a loan application. - What are the main risks of multifamily commercial investing?
Key risks include vacancy, unexpected repair expenses, rising interest rates and higher insurance costs. These factors can reduce property cash flow and make loan payments harder to support.
Sources & References :-
- Federal Reserve – Relevant to the article’s discussion of how monetary policy and borrowing costs influence commercial loan rates.
- Fannie Mae – Multifamily financing programs discussed in the article.
- Freddie Mac – Multifamily financing and long term apartment lending referenced in the article.
- HUD – Multifamily financing referenced for long term apartment investment.
- NSE/BSE style market data is not relevant here – This article is specifically about U.S. multifamily commercial real estate financing, so the relevant references are federal housing and lending sources rather than stock market sources.
- Article’s cited market framework – The article’s rate ranges, DSCR guidance, down payment ranges, fees and underwriting factors are the basis for the tables and FAQs above.
For More Updates Please Follow Click Here
Article was Last Updated on 30th August 2026.