

Best Bank FD Rates Today in India (2026) – Highest Interest Returns You Shouldn’t Miss
Introduction :
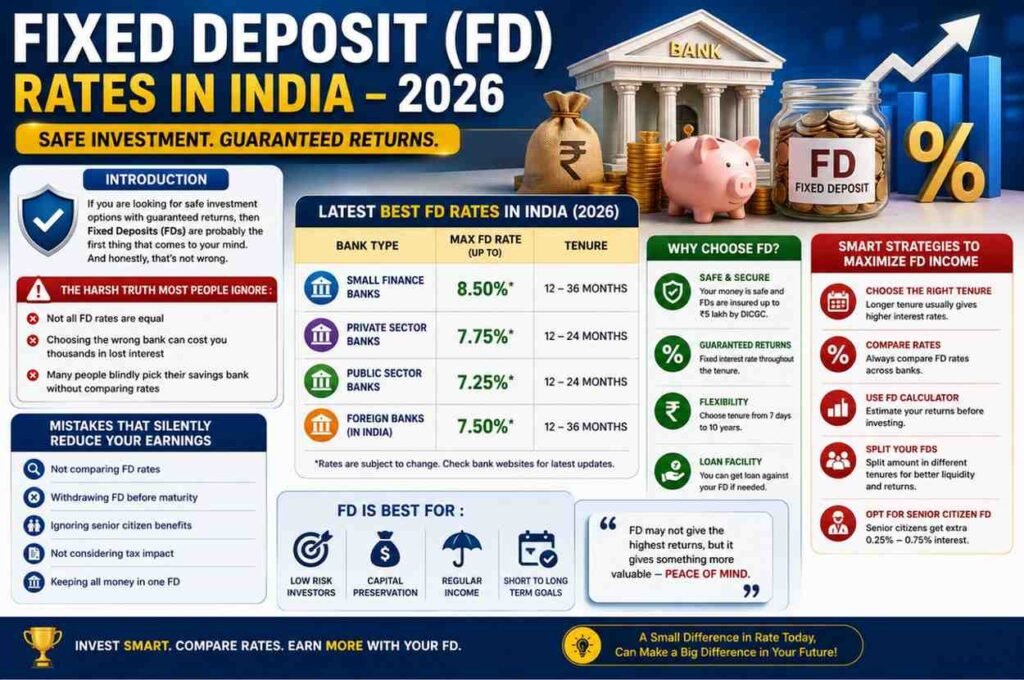
If you are looking for safe investment options with guaranteed returns, then Fixed Deposits (FDs) are probably the first thing that comes to your mind. And honestly, that’s not wrong.
But here’s the harsh truth most people ignore :
Not all FD rates are equal
Choosing the wrong bank can cost you thousands in lost interest
Many people blindly pic their savings bank without comparing rates
That’s exactly why these guide exists.
In this deep, practical, and fully updated article, you will learn.
Latest Best FD Rates in India (2026)
Which banks are actually giving highest returns
Smart Strategies to maximize your FD income
Mistakes that silently reduce your earnings.
Special Tips for Senior Citizens & Beginners :
This is not Generic Content – This is written to help you actually make better money decisions.
What is a Fixed Deposit (FD)
A Fixed Deposit (FD) is a financial instrument offered by banks where you :
Deposit a lumpsum amount
Lock it for a fixed tenure
Earn guaranteed interest
Unlike savings accounts, FD interest is much higher
Unlike stocks, FD has almost Zero Risk
Why FD is till Popular in 2026 :
Even which Mutual Funds & Stocks growing fast, FDs remain popular because :
Guaranteed Returns :
No market Fluctuation. You know your returns in advance
Capital Protection
Your Principle Amout Stay Safe
Ideal for Beginners
No Technical Knowledge required
Best for Senior Citizens
Extra interest Rates + Stable Income
Best Bank FD Rates Today in India (2026) :
Let’s get straight to what you came for
Important : FD rates change frequently, but below are latest competitive ranges.
Top banks offering highest FD rates
- State Bank of India (SBI)
Interest Rate 6.50% – 7.10%
Senior Citizens : + 0.50%
Best for : Safety + Trust
2. HDFC Bank
Interest Rate – 6.60% – 7.25%
Knowing for : Consistantt Returns
Good Digital Experience
3. ICICI Bank
Interest Rate – 6.70% – 7.20%
Best for : Flexible Tenure Options
4. AXIS Bank
Interest Rate – 6.50%- 7.250%
Good for Short term FDs
5. Pubjab National Bank
Interest Rate – 6.50% – 7.10%
Strong Government Backed Trust
6. IDFC First Bank
Interest Rate – 7.25% – 8.0%
One of the Highest FD Rates Currently
7. Bandhan Bank
Interest Rate – 7.50% – 8.25%
High Returns but Slightly Higher Perceived Risk
Reality Check : (Important)
Higher FD rate = Always better choice
Some smaller banks offer higher Interest because :
They need more deposits
They carry slightly higher risk
Always balance :
Return
Safety
Liquidity
FD Interest Rate Comparison Table :
| Bank Name | Regular Rate | Senior Citizen Rate | Safety Level |
| SBI | 6.5% – 7.1% | Up to 7.6% | Very High |
| HDFC | 6.6% – 7.25% | Up to 7.75% | Very High |
| ICICI | 6.7% – 7.2% | Up to 7.7% | Very High |
| AXIS | 6.5% – 7.25% | Up to 7.75% | High |
| PNB | 6.5% – 7.1% | Up to 7.6% | Very High |
| IDFC FIRST | 7.25% – 8% | Up to 8.5% | Medium |
| Bandhan | 7.5% – 8.25% | Up to 8.75% | Medium |
How to Choose The Best FD (Most People Get This Wrong)
- Don’t chase only high interest
If you blindly choose the highest rate :
You may compramise safety
2. Choose Based on your goal
Short term (1-2 years) – AXIS / ICICI
Longterm (5+ years) – SBI / HDFC
High Returns – IDFC / Bandhan
3. Check Bank Stability
Big Banks = Lower Risk
Small Banks = Higher Return but slightly more risk
Smart Strategies to Maximize FD Returns :
FD Laddering Strategy
Instead of investing 1 lakh in one FD :
Split into :
One year FD
Two year FD
Three year FD
This Gives :
Liquidity
Better average returns
Use senior citizen benefits
Extra 0.5% = overtime
Reinvest Interest :
Always choose cumulative FD for compounding
Mistakes you must avoid
Keeping all money in one bank
Ignoring inflations
Breaking FD early (Penalty)
Not comparing rates
FD vs Other Investment Options :
| Investment | Risk | Returns | Best For |
| FD | Low | 6-8% | Safety |
| Mutual Funds | Medium | 10-15% | Growth |
| Stocks | High | 15%+ | Wealth Building |
| Gold | Medium | 8-10% | Hedge |
Reality – FD alone wont make you rich
But it protects your money
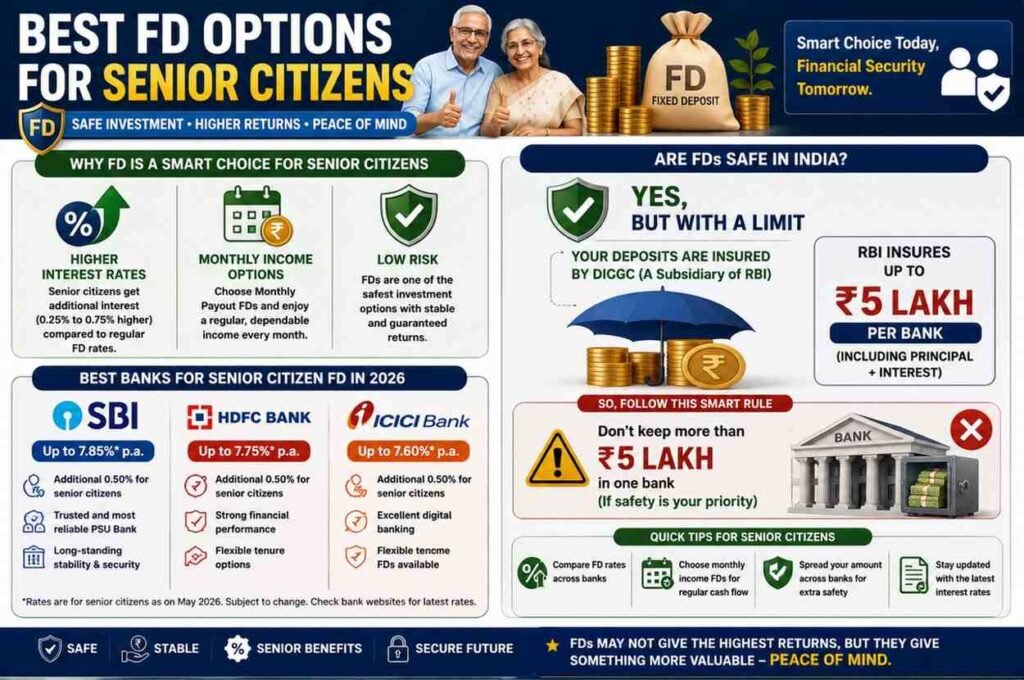
Best FD Options for Senior Citizens :
Higher Interest Rates
Monthly Income Options
Low Risk
Best Banks :
SBI
HDFC
ICICI
Are FDs Safe in India :
Yes, but which a limit
RBI insures upto 5 lakh per bank
So :
Don’t more than 5 lakh in one bank (If safety is priority).
Tax on FD Interest (Important)
FD interest is fully taxable
TDS applies if interest – 40,000
TIP : Use from 15G – 15H If eligible
When is the Best Time to Invest in FD :
When interest rates are high
When RBI increases Repo Rate
2026 is currently a good window for FD investors
Who Should Invest in FD :
Beginners
Retired People
Risk Awares Investors
Emergency Fund Planners
Frequently Asked Questions (FAQs)
- Which Bank gives highest FD Interest Today ?
IDFC First Bank & Bandhan Bank currently offers highest rates (8%+)
2. Is FD better than Mutual Funds ?
Safer, but lower returns
3. Can i Break FD anytime ?
Yes, but penalty applies
4. How much FD is Taxfree ?
No, FD is completly Taxfree (Except Special Schemes)
5. Is FD 100% Safe ?
Safe upto 5 Lakh per bank.
6. What is FD laddering and how does it work ?
FD laddering means splitting your money across different maturities instead of putting everything into one FD. It can improve liquidity and reduce risk of locking all your money at one rate.
7. Is a higher FD interest rate always better ?
No, A higher rate should be considered along with bank stability, deposit insurance, tenure, premature withdrawal conditions and your liquidity needs.
8. With FD is better for monthly income ?
A non cumulative or monthly interest payout FD can be useful when you need regular cash flow. The exact payout and interest calculation depend on the bank and deposit option.
9. How much money should I keep in one bank FD ?
There is no universal limit for how much you should invest in one bank. If deposit insurance protection is your priority, remember that DICGC coverage is capped at 5 lakh depositor per bank, including principal and interest.
10. Is FD better than mutual funds ?
FDs are generally better suited to investors prioritising predictable returns and lower market risk, while mutual funds are designed for market linked growth and carry investment risk. The right choice depends on your goal and risk tolerance.
Sources & References :-
- DICGC – Deposit Insurance FAQ – confirms deposit insurance up to 5 lakh depositor per bank, including principal and interest.
- Income Tax Department – Senior Citizens & Super Senior Citizens AY 2026-27 – current 2026 tax information, including Section 80TTB and the 1 lakh senior citizen TDS threshold.
- Income Tax Department – TDS Compliance – current 2026 TDS framework following the transition to the Income Tax Act, 2025.
- RBI – Master Direction on Interest Rate on Deposits – premature withdrawal, deposit terms and senior citizen deposit provisions.
- RBI – FAQs on Interest Rate on Deposits – explains premature withdrawal penalties and depoist interest rules.
Conclusion :
Let’s be very clear :
FD is not for getting rich
FD is for protecting and stabilizing your money
If you play it Smart :
Choose the Right Bank
Use Laddering
Avoid Mistakes
You Can Maximize Returns without Risk
For More Updates Please Follow Click Here
Article was Last Updated on 13th August 2026.